Impact-Resistant Shingles: Are They Worth the Investment in Maryland?
The upgrade usually shows up as a single line on an estimate. Class 4 impact-resistant shingles are an added cost, and no real explanation of what that buys you in a state where softball-sized hail is a once-in-a-decade curiosity rather than an annual event. Most homeowners either take it on faith or decline it on price, and neither of those is a decision.
The honest case for impact-resistant shingles in Southern Maryland has almost nothing to do with the hail-belt marketing that surrounds the product. It rests on a Maryland insurance statute most homeowners have never heard of, on wind-driven debris rather than hailstones, and on how the asphalt itself ages. G.H. Clark Contractors has installed roofs across Calvert, Anne Arundel, and St. Mary’s counties for more than 30 years, and this particular upgrade deserves a clearer answer than most homeowners get.
What Are Impact-Resistant Shingles?
Impact-resistant shingles are asphalt shingles engineered to absorb a strike without fracturing the mat underneath. They are tested under UL 2218 or ANSI/FM 4473 and assigned a class from 1 to 4, with Class 4 representing the highest impact resistance available on a residential roof.
The rating measures one narrow thing: whether the shingle body cracks when something hits it hard. That is not the same as being stormproof, and it says nothing about wind performance, fire rating, or service life. A Class 4 shingle carries its own separate wind classification and its own separate fire rating, and neither number has any relationship to the impact class. Knowing what the label does not cover is as useful as knowing what it does.
How Does the Class 1 Through Class 4 Rating Work?
UL 2218 drops a steel ball onto a mounted roof deck from a set height. Class 1 uses a 1.25-inch ball from 12 feet and Class 4 uses a 2-inch ball from 20 feet, with drop heights calibrated to the energy a hailstone of that diameter carries at terminal velocity.
| UL 2218 Class | Steel Ball Diameter | Drop Height | Hailstone Equivalent |
|---|---|---|---|
| Class 1 | 1.25 inches | 12 feet | About the size of a half-dollar |
| Class 2 | 1.50 inches | 15 feet | About the size of a walnut |
| Class 3 | 1.75 inches | 17 feet | About the size of a golf ball |
| Class 4 | 2.00 inches | 20 feet | About the size of a hen egg |
Passing means something specific. After the strike, the sample is inverted, bent over a mandrel, and examined for any crack or opening on the back surface. Denting on the visible face is permitted. A Class 4 shingle can look damaged from the ground and still be performing exactly as rated, which is a distinction that matters a great deal during a claim. The competing ANSI/FM 4473 standard tests the same idea by firing actual ice balls instead of dropping steel.
How Are Impact-Resistant Shingles Actually Made?
Manufacturers use one of two approaches. Some bond a mesh or scrim to the back of the shingle to hold it together under impact. Others blend polymer modifiers into the asphalt itself, producing a shingle that looks identical to a standard product but flexes instead of fracturing.
The difference matters more than the shared Class 4 label suggests. Research from the Insurance Institute for Business and Home Safety notes that reinforcement backing can conceal fractures during inspection, and neither UL 2218 nor FM 4473 requires examining the internal reinforcement layer. A scrim-backed shingle can pass the test carrying hidden damage in the mat.
Polymer-modified shingles have no such blind spot, because the resistance comes from the asphalt chemistry rather than from a layer bonded underneath. Ask which construction you are being quoted. Two products wearing the same rating are not the same product.
How Much Hail Does Maryland Actually Get?
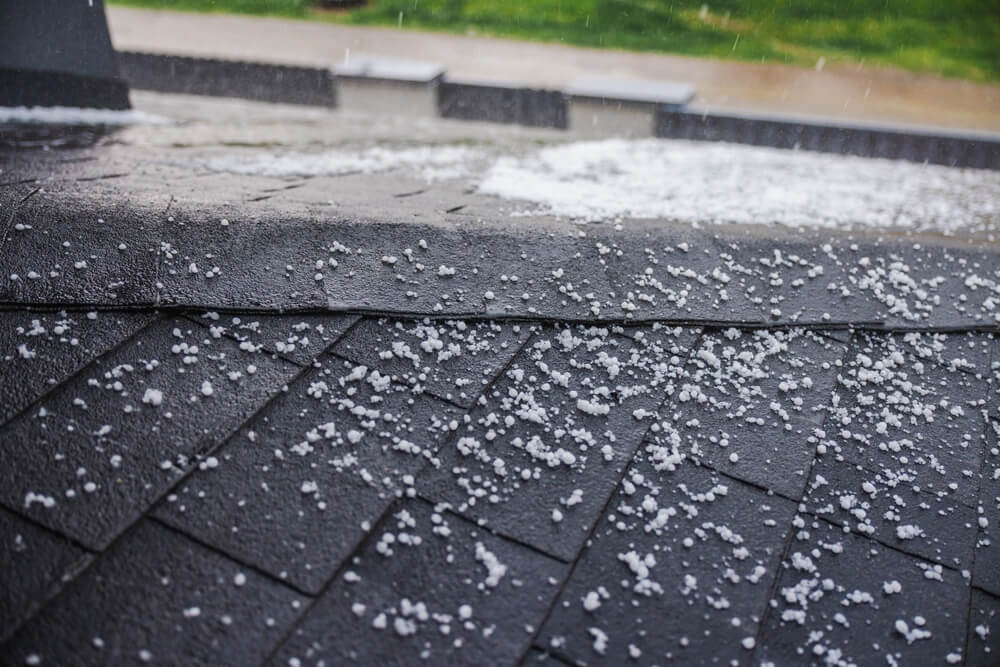
Not much. Maryland recorded roughly 1,523 hail events between 1955 and 2024 in the NOAA Storm Prediction Center archive, ranking 33rd among the 50 states. The state sits well outside the central Plains corridor where damaging hail is a seasonal certainty rather than an occasional surprise.
The comparison that matters most is internal. Across a similar span, Maryland’s record shows roughly 7,836 damaging-wind events against about 1,528 hail events — wind outnumbers hail in this state by close to five to one. A homeowner in Huntingtown or Lusby stands a far better chance of losing shingles to a nor’easter than to a hailstorm.
Size matters as much as frequency. The National Weather Service classifies a thunderstorm as severe at one-inch hail, and two-inch stones — precisely the threat Class 4 is built against — generally require supercell conditions the Mid-Atlantic rarely produces. Local hail season runs March through June, peaking in April and May.
Does Maryland Law Require an Insurance Discount for These Roofs?
Yes, in a limited but useful way. Section 19-210 of the Maryland Insurance Code requires insurers to offer at least one actuarially justified premium discount to policyholders who document storm-mitigation improvements, and the statute names reinforced roof coverings explicitly as a qualifying improvement.
What the law compels is the offer, not any particular number. Each carrier sets its own actuarially justified percentage, which means two homeowners on the same street in Dunkirk can receive very different credits for identical roofs. The only way to learn your figure is to ask your carrier directly before you commit to the upgrade.
The statute lists reinforced roof coverings alongside hurricane shutters and secondary water barriers as qualified mitigation actions. That placement is the point. Maryland regulators treat a reinforced roof covering as genuine storm mitigation, which is a stronger endorsement than any manufacturer brochure.
How Do You Actually Claim the Discount?
Your insurer must send an annual statement describing the discount’s availability and the method of applying for it. The improvement has to be inspected by a contractor licensed by the Maryland Department of Labor, and final verification of that improvement rests with the insurer.
The annual notice is the piece most homeowners miss. It arrives with renewal paperwork, reads like boilerplate, and goes straight into the recycling. If you installed a qualifying roof and never applied, the credit is simply not running.
- Confirm the specific product and its class before shingles are ordered
- Keep the manufacturer’s data sheet showing the UL 2218 classification
- Keep the itemized contract identifying the exact shingle installed
- Get the installing contractor’s Maryland license number in writing
- Read the annual mitigation-discount notice your carrier is required to send
What About Wind and Falling Debris?
This is where impact resistance earns its keep in Southern Maryland. Wind-borne branches, falling limbs, and debris driven by nor’easters and tropical storm remnants strike roofs far more often here than hail does, and a shingle built to survive a two-inch stone survives a limb strike better as well.
Tree cover is the variable that decides it. A house on a cleared lot near the water in Solomons faces a different threat profile than one tucked into mature oaks outside Sunderland. Wooded properties across Calvert and St. Mary’s counties take limb strikes every storm season, and the resulting damage tends to be localized punctures rather than the widespread bruising a hailstorm leaves behind.
The two damage patterns look different on a roof, and telling them apart matters at claim time:
- Limb and debris strikes: scattered punctures, gouges, and scrape marks along one slope
- Hail bruising: evenly distributed dents and granule loss across every exposed face
- Wind damage: creased, lifted, or missing shingles concentrated at rakes and ridges
Impact resistance was engineered for hail, but the physics carry over. Anything arriving with enough energy to fracture a shingle mat meets the same resistance, whether it fell from a cloud or from a tree.
How Do Wind and Hail Deductibles Change the Math?
Many Maryland policies carry a separate percentage deductible for hurricane, named storm, wind, or hail rather than a flat dollar amount. A large percentage deductible can make modest claims not worth filing, which shifts the value of the upgrade away from claim payouts and toward avoiding damage in the first place.
Maryland regulation restricts when those percentage deductibles apply. A hurricane warning must be issued for the part of the state where the property sits before a percentage deductible can be triggered for a hurricane or other storm. Homeowners in Anne Arundel and Calvert counties should know which deductible their policy applies to which peril, because the answer is rarely the same for all of them.
Payout structure matters too. A replacement cost policy typically pays actual cash value first and releases the recoverable depreciation once the work is finished. A roof that resists damage never enters that process at all.
Do These Shingles Last Longer Even Without Hail?
Polymer-modified shingles generally do. The same modifiers that let the asphalt absorb an impact also keep it flexible through temperature swings, which slows the embrittlement that ends most asphalt roofs in the Mid-Atlantic.
Maryland roofs cycle hard. Summer surface temperatures near the Chesapeake Bay run high, winter delivers repeated freeze-thaw, and asphalt sheds volatile oils and stiffens a little more with every cycle. Brittle shingles crack at the nail line, shed granules faster, and lift at the sealant strip. Modified asphalt resists that progression.
Scrim-backed products deliver no comparable benefit, since the reinforcement addresses impact alone and leaves the asphalt chemistry unchanged. That is the second reason to ask which construction you are buying.
So Are They Worth It for a Maryland Home?
It depends on three things: what your carrier will actually credit, how much tree cover surrounds the house, and whether the product is polymer-modified or scrim-backed. The hail argument that sells these shingles across the Plains does not carry the decision here.
Call your insurance carrier before you sign a roofing contract. A meaningful annual credit compounds across the life of a roof and can settle the question on its own. A token credit leaves the decision resting on debris protection and durability.
The upgrade makes clear sense when several of these are true:
- Heavy mature tree cover stands close to the house
- Your carrier offers a substantial documented mitigation credit
- The product is polymer-modified rather than scrim-reinforced
- You plan to stay long enough to recover the premium
It makes considerably less sense on an open, cleared lot, with a carrier offering only a nominal credit, or when a move is coming soon enough to close the payback window.
Schedule a Free Roofing Estimate in Southern Maryland
The upgrade is worth what your carrier says it is worth plus whatever your trees demand, and both of those are answerable before you spend anything. G.H. Clark Contractors has served homeowners from Prince Frederick to Leonardtown for more than 30 years as a family-owned business answerable to the homeowner rather than to any manufacturer. Our estimates identify the specific shingle and its classification in writing, so you hold the documentation your insurer will ask for. We will also tell you plainly when the upgrade does not make sense for your property. Estimates are free and delivered without sales pressure, and financing is available.
Call G.H. Clark Contractors at (410) 414-7060 to schedule your free roofing estimate.
Frequently Asked Questions About Impact-Resistant Shingles
Can you tell an impact-resistant shingle by looking at it?
Usually not. Polymer-modified shingles are visually identical to standard products because the difference sits in the asphalt chemistry. Scrim-backed versions show a mesh on the underside, visible only before installation. The reliable confirmation is the manufacturer’s data sheet listing the UL 2218 classification.
Does a Class 4 rating weaken as the roof ages?
Effectively, yes. The classification reflects performance on a new shingle tested in a laboratory. Asphalt stiffens over time as it loses volatile oils, and an aged shingle of any class absorbs impact less readily than it did on installation day. Polymer-modified products slow that decline without stopping it.
Will an insurer accept a Class 3 shingle for a discount, or only Class 4?
That varies by carrier. Maryland law requires the offer of at least one actuarially justified discount for qualified mitigation, but each insurer defines which products qualify. Most carriers that credit impact resistance require Class 4. Confirm the requirement in writing before material gets ordered.
Do impact-resistant shingles need special installation?
They install much like any architectural shingle, though manufacturers often specify a particular nail count and accessory system to keep the full warranty intact. Some scrim-backed products are stiffer in cold weather and call for more care during winter work.
Are they available in the same colors and profiles as standard shingles?
Generally yes, though the selection runs narrower. Impact-resistant lines typically offer a subset of the colors available in a manufacturer’s standard architectural range. If a specific color is driving your decision, confirm availability before committing to the upgrade.
What documentation should you keep to claim the discount?
Keep the itemized contract naming the exact shingle installed, the manufacturer’s data sheet showing the UL 2218 class, and the installing contractor’s Maryland license number. Your carrier may also require an inspection by a licensed contractor, since verification of the improvement rests with the insurer.